8.2 Compositions and Inverse Transformations: Class Notes
Definition
If is a linear transformation from a vector space to a vector space , then is said to be one-to-one if maps distinct vectors in into distinct vectors in .
OR is one-to-one if and only if for each vector in the range of , there is exactly one vector in such that .
OR is one-to-one if and only if implies .
Definition
If is a linear transformation from a vector space to a vector space , then is said to be onto (or onto W) if every vector in is the image of at least one vector in .
Examples
One-to-one and onto:
- Rotation operators on ()
- where
- where
One-to-one but not onto:
- , where
Not one-to-one:
- , where . Example: .
Theorem 8.2.1
If is a linear transformation, then is one-to-one if and only if .
Recall
Proof
() By Theorem 8.1.1, because is linear. If is one-to-one and if , then by definition. Thus .
() Let such that . Then , so, since and is linear,
#4
Determine whether the linear transformation is one-to-one by finding its kernel and then applying Theorem 8.2.1.
a. , where
b. , where
c. , where
Solution
a.
These are all equivalent to , a line through the origin, so . The kernel contains nonzero vectors such as .
Answer:
b. . Since this means , this is again a line through the origin, so .
Answer:
c. . If
then, adding, . So .
Answer:
#5
Determine whether multiplication by is one-to-one by computing the nullity of and then applying Theorem 8.2.1.
Solution
a.
. Since has 2 columns and , .
Since , .
Answer:
b. has 4 columns but (it has only 3 rows). Since , .
Answer:
Theorem 8.2.X
If is a one-to-one linear transformation and is a linearly independent subset of , then is linearly independent.
That is, a one-to-one transformation preserves linear independence.
Proof
Suppose
Then, because is linear,
Since is one-to-one (so ),
Then because is linearly independent. It follows that is linearly independent.
Theorem 8.2.2
If and are finite-dimensional vector spaces with the same dimension, and if is a linear transformation, then the following statements are equivalent.
a) is one-to-one.
b) .
c) is onto [i.e., ].
is the range of .
Proof
a b is established by Theorem 8.2.1.
b c: Assume . We know that (Theorem 8.1.4).
Theorem 8.2.3
If is a matrix transformation, then
a) is one-to-one if and only if the columns of are linearly independent.
b) is onto if and only if the columns of span .
Proof
a) is one-to-one if and only if , which holds if and only if (since ). Thus the columns of are linearly independent (a basis for is the pivot columns).
b) is onto has a solution for all every is in the columns of span .
#14
Use Theorem 8.2.3 to determine whether multiplication by is one-to-one, onto, both, or neither. Justify your answer.
Solution
a) Not onto: 2 columns can’t span . One-to-one: for any , so the two columns are linearly independent.
Answer:
b) Not one-to-one: and , so the columns are not linearly independent.
2 pivots, so and the columns do not span . Not onto.
Answer:
c) , so is not one-to-one (the columns are linearly dependent). It is also not onto (the columns don’t span ).
Answer:
d) , so is invertible and its columns are linearly independent and span : one-to-one and onto.
Answer:
If with shaped like a wide matrix (more columns than rows), then is not one-to-one. If is shaped like a tall matrix (more rows than columns), can’t be onto.
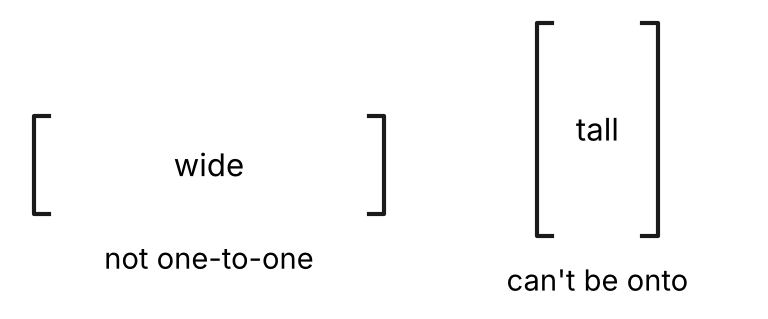
A wide bracketed matrix, labeled not one-to-one, next to a tall bracketed matrix, labeled can’t be onto.
In the same way, for :
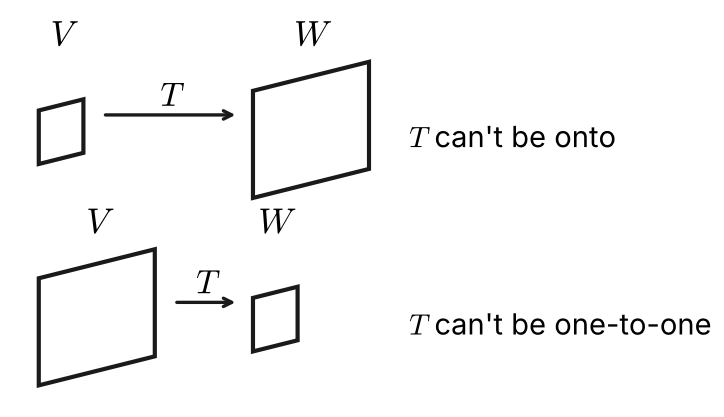
Top: is drawn smaller than , and can’t be onto. Bottom: is drawn larger than , and can’t be one-to-one.
Theorem 8.2.4 Equivalent Statements (extends Theorems 4.9.8, 5.1.5 and 6.4.5, the last two of which we have not seen)
If is an matrix, then the following statements are equivalent.
a) is invertible.
b) has only the trivial solution.
c) The reduced row echelon form of is .
d) is expressible as a product of elementary matrices.
e) is consistent for every matrix .
f) has exactly one solution for every matrix .
g) .
h) The column vectors of are distinct and linearly independent.
i) The row vectors of are distinct and linearly independent.
j) The column vectors of span .
k) The row vectors of span .
l) The column vectors of form a basis for .
m) The row vectors of form a basis for .
n) has rank .
o) has nullity 0.
p) The orthogonal complement of the null space of is .
q) The orthogonal complement of the row space of is .
r) is not an eigenvalue of . [This is from Theorem 5.1.5.]
s) is invertible. [This is from Theorem 6.4.5.]
t) The kernel of is .
u) The range of is .
v) is one-to-one.
Statements t), u), and v) are the new additions.
Perspectives
If is an matrix, a subspace of (input side) can be considered as:
- The null space of (matrix view)
- The solution space of (system view)
- The kernel of (transformation view)
A subspace of can be considered as:
- The column space of (matrix view)
- All such that is consistent (system view)
- The range of (transformation view)
Definition
If is a one-to-one linear transformation with range , and if is any vector in , then there is exactly one vector in for which . The inverse of T maps back into and is denoted by . (This is analogous to inverse in Section 1.9.)
Definition: (analogous to composition in Section 1.9)
If and are linear transformations, then the composition of with , denoted by (which is read “ circle ”) is the function defined by the formula where is a vector in .
Note that the order of composition matters.
Theorem 8.2.5
If and are linear transformations, then is also a linear transformation.
Tip: This is a good proof to practice.
Recall
is a linear transformation if and only if homogeneity and additivity hold. That is, if and .
Proof
Let and .
Therefore is linear.
Theorem 8.2.6
If and are one-to-one linear transformations, then:
a) is one-to-one.
b) .
#38
Let and be the derivative and integral linear transformations. Find for
a.
b.
Solution
a) First apply , then :
Answer:
b) , so
Answer:
Key concepts from 8.3
Definition
A linear transformation that is both one-to-one and onto is said to be an isomorphism, and is said to be isomorphic to .
Theorem 8.3.1
Every real -dimensional vector space is isomorphic to . [In this sense, every -dimensional vector space is algebraically equivalent to .]
Theorem 8.3.2
If is an ordered basis for a vector space , then the coordinate map is an isomorphism between and .
Theorem 8.3.X
A linear transformation is an isomorphism if and only if whenever is a basis for , is a basis for .
Examples of Natural isomorphisms
Between and :
Between and :